

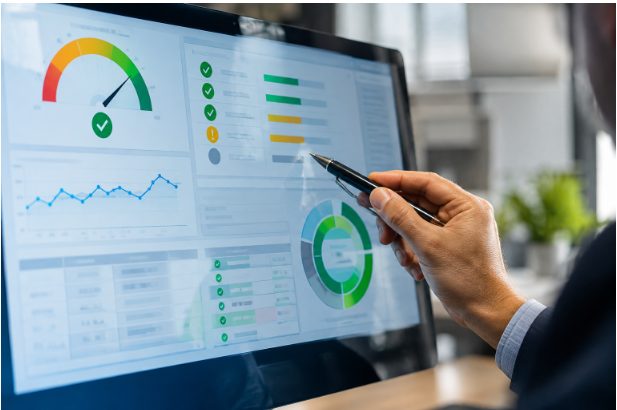
Key Takeaways
- AI can support faster credit decisions, but speed should never replace careful review.
- Reliable, relevant, and well-governed data is the foundation of any useful credit model.
- Teams should test models for performance, bias, drift, and explainability before and after launch.
- Customers need specific, understandable reasons when an adverse credit action is taken.
- Human oversight remains necessary when a decision could materially affect a customer's financial future.
For financial services teams in St. Croix and across the U.S. Virgin Islands, artificial intelligence can improve the speed and consistency of credit work, but only when it is used with disciplined controls. Organizations connected to Kirk Chewning Cane Bay Partners and the wider local financial services community can view trustworthy AI as an operating practice, not merely a technology purchase.
Credit decisions can shape whether a household can manage an unexpected expense, finance a vehicle, or access other important opportunities. That makes accuracy, fairness, clear communication, and accountable human judgment essential, especially when an automated score or recommendation influences the outcome.
Why Trust Matters in AI-Based Credit Decisions
Credit models do more than sort routine tasks. They influence real financial outcomes for applicants and risk outcomes for lenders. A model might increase approvals while failing to recognize warning signs of repayment stress, creating avoidable losses and difficult customer experiences. Trust comes from balancing efficient decisions with sound controls, rather than treating approval volume as the only measure of success.
Start With a Clear Business Problem
Define the operational problem before selecting a model or software platform. A narrow use case, such as prioritizing applications for review, detecting potentially inconsistent application information, or reducing repetitive manual checks, is easier to measure and govern than a broad automation initiative. Establish success measures in advance, including decision time, predictive performance, customer outcomes, review volumes, and fairness indicators.
Build a Strong Data Foundation
Advanced modeling cannot correct unreliable inputs. Teams should check for missing fields, duplicate records, outdated information, unusual values, and changes in how a source system captures data. Document where each field originates, who owns it, how often it is refreshed, and why it has a meaningful relationship to the credit decision. If a data element cannot be justified, it deserves closer scrutiny before it enters a model.
Choose the Right Model for the Job
A simpler statistical scorecard may be the better choice when it performs adequately and can be readily tested and explained. More complex machine learning approaches may be appropriate when they yield a meaningful improvement that the organization can validate, monitor, and translate into decision-making. The practical choice weighs predictive value against cost, speed, operational resilience, and explainability.
Test for Fairness and Unwanted Bias
Bias can arise from historical lending patterns, incomplete records, proxy variables, or differences in how data is collected. Before deployment, test approval rates, pricing outcomes, false-positive and false-negative rates, and model errors across relevant groups. The AI Risk Management Framework provides a useful, voluntary structure for organizing governance, measurement, and risk management work for AI systems.
Make Model Decisions Easier to Explain
Technical accuracy is not enough if staff cannot identify the major factors driving an outcome. Build an explanation process that produces consistent, plain-language reasons for front-line teams, auditors, compliance professionals, and customers. A useful explanation reflects the factors actually used in the decision, rather than relying on a generic list that may not match the model's output.
Keep Human Review in the Process
Human review is particularly valuable for unusual applications, thin credit files, conflicting information, identity concerns, or outcomes that fall near an approval threshold. Reviewers need clear authority to pause a decision, request more information, or override a result when justified. Track those overrides, including their reasons, because recurring patterns can reveal weaknesses in the data, policy, or model.
Meet Customer Communication Duties
When a credit decision is denied, limited, or adversely changed, customer communication should be clear, specific, and connected to the actual decision-making process. The requirements for adverse action notices make clear that using a complex algorithm does not remove the need to provide accurate reasons. Legal, compliance, operations, and customer experience teams should review these messages together.
Monitor Models After Launch
A model that performs well at launch can weaken as applicant behavior, economic conditions, products, and data sources change. Monitor data quality, approval rates, repayment performance, complaints, exception volumes, and differences between expected and actual outcomes. A practical rhythm includes automated alerts for major changes, monthly performance reporting, and deeper quarterly reviews that can trigger recalibration, retraining, or retirement.
Create a Practical Governance Checklist
- Assign named business, model-risk, compliance, and technology owners.
- Maintain documented data sources, model assumptions, testing results, and approval rules.
- Keep version histories for models, training data, policies, and customer notices.
- Define escalation steps for poor performance, unexpected outcomes, complaints, or outages.
- Schedule regular discussions among data science, risk, legal, operations, and customer service teams.
Common Mistakes to Avoid
Common failures include launching before data is validated, choosing complexity over clarity, reusing historical decisions without testing for unfair patterns, and issuing generic reasons that do not reflect the actual decision. Governance should not be treated as paperwork completed at launch. It is the ongoing process that prepares the organization for updates, exceptions, outages, and changing customer conditions.
A Simple Action Plan
- Select one credit decision with a specific, measurable goal.
- Map the data and current decision process from intake through finance.
- Test data quality, model performance, and potential bias.
- Compare simpler and more complex model options.
- Design customer explanations and review procedures before deployment.
- Run a controlled pilot with human oversight.
- Measure business results alongside customer and fairness outcomes.
- Set ongoing monitoring, escalation, and governance review schedules.
Conclusion
Trustworthy AI credit decisions are built through steady operational discipline. For St. Croix financial services teams, the goal is not to eliminate judgment from lending, but to combine data-driven insight with clear explanations, accountable people, and active monitoring. That approach can support responsible innovation while helping customers and institutions rely on the decisions being made.


2 thoughts on “Building Trustworthy AI Credit Decisions: A St. Croix, U.S. Virgin Islands Guide for Financial Services Teams”
Comments are closed.