Businesses are constantly looking for better ways to manage transactions, protect information, and work with customers and partners. However, traditional systems often involve multiple intermediaries, disconnected databases, lengthy verification processes, and limited visibility into transactions.
These challenges are creating opportunities for blockchain technology. Although blockchain originally gained attention through cryptocurrencies, its applications now extend to financial services, supply chains, healthcare, real estate, retail, and enterprise operations.
With blockchain development, businesses can build applications that support transparent recordkeeping, digital asset management, automated agreements, and secure information sharing.
Imagine a supply chain where authorized participants can verify a product’s recorded journey without repeatedly requesting documents from different companies. Or a business agreement where predefined payment instructions execute automatically after verified conditions are fulfilled. Blockchain can make these workflows possible.
The real opportunity lies in using blockchain to solve existing business problems and develop services that were previously difficult to coordinate. Understanding where the technology adds value is the first step toward making a worthwhile investment.
What Is Blockchain Development and How Does It Work?
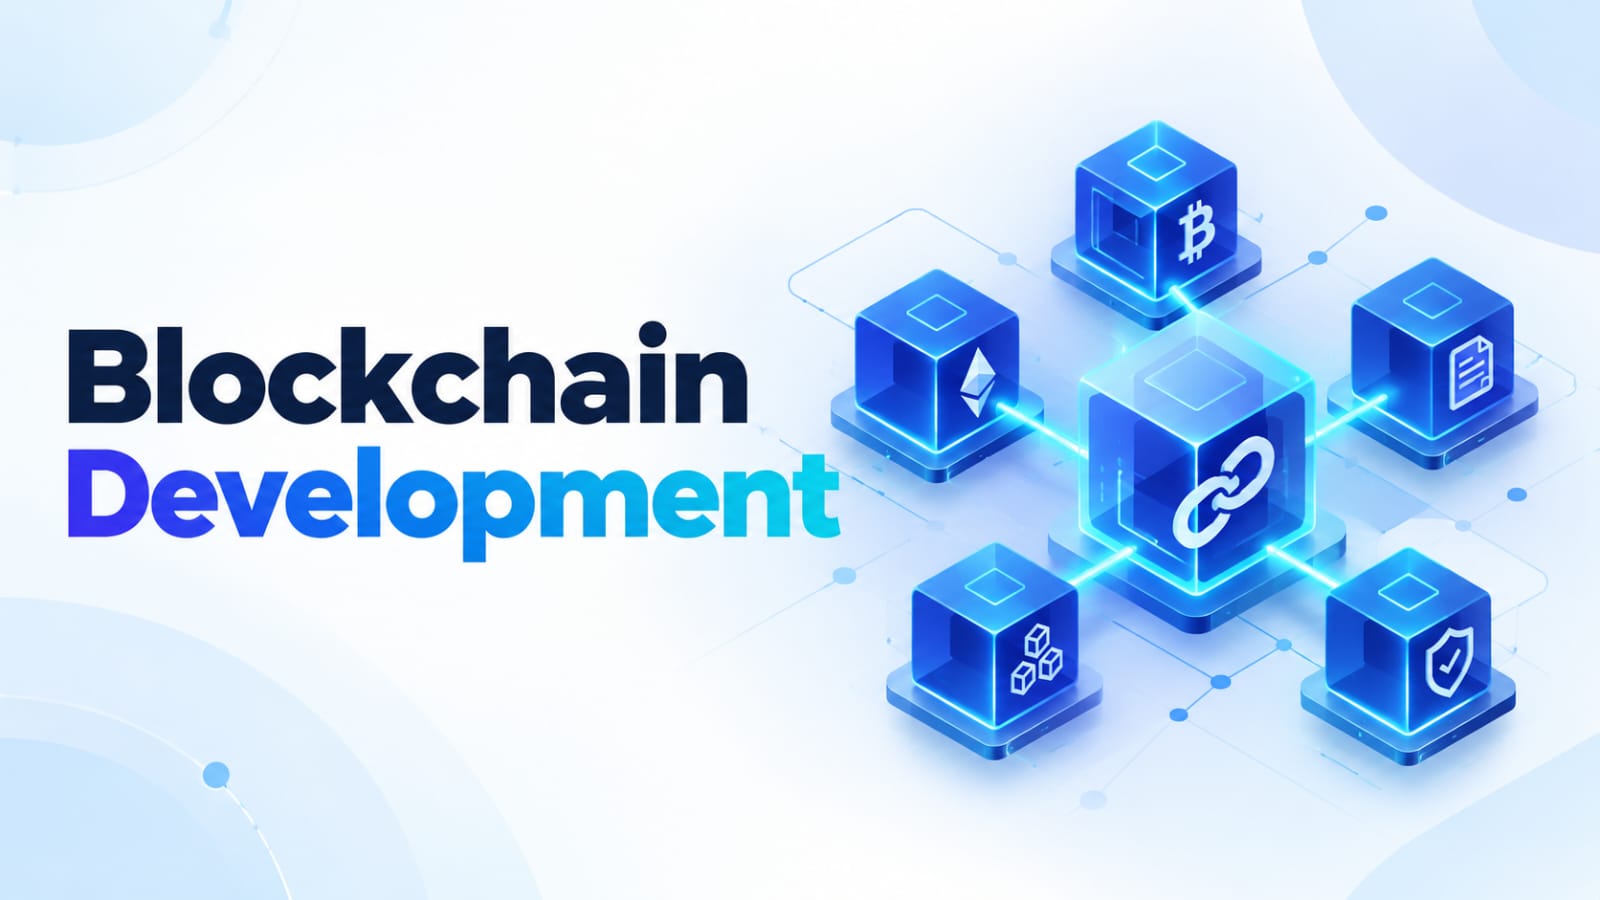
Blockchain development is the process of creating applications and systems using distributed ledger technology. A blockchain records transactions in cryptographically linked blocks, allowing network participants to verify and maintain a shared transaction history.
Unlike a traditional database managed by a single organization, blockchain can distribute responsibility for maintaining records among multiple participants.
When someone submits a transaction, the network validates it according to predefined rules. Approved transactions are recorded on the ledger, making subsequent unauthorized changes difficult to conceal.
Businesses can use blockchain for different purposes, including financial transactions, asset tracking, digital identity verification, and smart contract execution.
Understanding the Core Components of Blockchain
A blockchain application typically relies on several essential components:
- Distributed ledger: Maintains synchronized transaction records across participating systems.
- Consensus mechanism: Determines how the network agrees on valid transactions.
- Cryptography: Helps authenticate transactions and protect data integrity.
- Smart contracts: Execute programmed instructions when specified conditions are satisfied.
- Network nodes: Participate in maintaining, validating, or accessing blockchain records.
Blockchain networks can be public, private, or consortium-based. The appropriate choice depends on who needs access, how transactions are validated, and what level of governance the business requires.
Why Is Blockchain Development Important for Businesses?
Modern organizations exchange enormous amounts of information with suppliers, customers, banks, distributors, and business partners. When each participant maintains separate records, disagreements and reconciliation requirements can slow down operations.
Blockchain can create a shared record of transactions that participating organizations can independently verify.
For example, manufacturers and distributors can use a permissioned blockchain network to record shipment details, product ownership changes, and delivery confirmations.
Instead of depending entirely on separate documents, authorized participants can reference a consistent transaction history.
The technology can also support automation. Smart contracts allow businesses to execute predefined actions without manually processing every transaction.
However, blockchain is most valuable when several parties need shared, verifiable records. A conventional database may remain the better option when a single organization controls the entire process.
Key Business Opportunities Created by Blockchain Development
Blockchain development is opening opportunities for organizations to improve existing processes and introduce new digital business models.
1. Building More Transparent Business Operations
Transparency is important when organizations need to verify transactions involving multiple participants.
Blockchain records can provide a consistent history of activities, helping authorized parties track changes and investigate discrepancies.
For example, a manufacturer can record when goods are produced, inspected, dispatched, and received. Supply chain partners can review these events to understand the recorded movement of products.
Although blockchain cannot guarantee that the original information is accurate, it can help businesses maintain tamper-evident records and establish clearer accountability.
2. Automating Agreements With Smart Contracts
Traditional business agreements often require manual approvals, document verification, and coordination between different departments.
Smart contracts introduce an alternative by executing predefined instructions on a blockchain network.
Consider a logistics company that agrees to release payment after successful delivery. A smart contract could initiate the payment once an authorized external system provides verified confirmation.
This approach can reduce repetitive administrative steps and support more consistent execution of agreed business rules.
When combined with business process automation, smart contracts can become part of broader workflows involving payment systems, enterprise applications, and operational approvals.
3. Creating New Digital Payment Opportunities
Blockchain technology supports the transfer of digital assets between participants without requiring every transaction to pass through a traditional centralized ledger.
Businesses can explore blockchain-based solutions for international payments, digital asset transfers, and programmable settlements.
For instance, a company working with international suppliers might evaluate blockchain-based settlement options to simplify specific payment processes.
However, actual benefits depend on transaction costs, network reliability, currency conversion, banking arrangements, and regulatory requirements.
4. Introducing Digital Asset Tokenization
Tokenization allows businesses to represent certain assets, rights, or interests through blockchain-based digital tokens.
Potential applications include digital collectibles, membership rights, eligible financial instruments, and ownership records.
A company could create a token-based membership system in which customers hold verifiable digital credentials providing access to selected services.
Tokenization can also support the development of specialized digital marketplaces.
Its commercial value depends on whether the underlying rights are legally recognized, securely managed, and useful to customers.
5. Developing Decentralized Applications
Decentralized applications, commonly called dApps, use blockchain networks or smart contracts to provide selected application functions.
These applications can support digital wallets, marketplaces, financial services, community platforms, and asset management.
For businesses exploring new digital products, dApps create opportunities to design systems that operate through shared network rules rather than depending entirely on a central application operator.
Successful development still requires reliable interfaces, secure code, user-friendly onboarding, and integration with supporting services.
This part matters more than in most software, since many users are new to wallets and transactions, so design for web3 companies tends to focus on making every step understandable before anything is signed.
6. Improving Digital Identity Verification
Businesses regularly verify customer identities, employee credentials, and organizational documents.
Blockchain can support verifiable digital credentials that allow authorized parties to check authenticity without repeatedly contacting the original issuer.
For example, educational institutions could issue digitally signed qualifications that employers can verify.
Sensitive personal information should generally remain outside an immutable public ledger, while cryptographic references and credential verification mechanisms support authenticity checks.
Industries Exploring Blockchain Development Opportunities
Blockchain has potential applications across industries where transactions involve multiple parties, asset ownership, or shared business records.
Financial Services and Banking
Financial organizations are exploring blockchain for cross-border settlements, digital assets, trade finance, and transaction reconciliation.
Shared ledgers can help participating institutions coordinate transactions and maintain consistent records, potentially reducing selected administrative tasks.
Supply Chain and Logistics
Blockchain can support product traceability by recording manufacturing activities, shipment movements, inspections, and delivery confirmations.
For example, food distributors can use blockchain-connected tracking systems to trace recorded product batches through the supply chain.
This can improve access to information during product recalls and quality investigations.
Healthcare and Pharmaceuticals
Healthcare organizations can explore blockchain for credential verification, pharmaceutical tracking, and integrity checks on medical information.
For example, pharmaceutical companies could record product movements across distributors and healthcare facilities.
Patient information still requires appropriate privacy controls, secure storage, and compliance with applicable healthcare regulations.
Real Estate
Real estate businesses can explore blockchain for property transaction workflows, document verification, and tokenized asset structures.
Smart contracts may automate selected administrative steps, while blockchain records can help participants verify transaction histories.
Legal ownership transfers must still follow applicable property laws and registration requirements.
Retail and E-commerce
Retailers can investigate blockchain-based product authentication, loyalty programs, digital payments, and supply chain records.
For example, a luxury goods retailer might provide customers with a blockchain-verifiable product authenticity certificate linked to its inventory system.
How Blockchain Development Improves Business Efficiency?
Blockchain can improve efficiency when companies repeatedly exchange and reconcile records across different organizations.
A shared transaction history can reduce some manual verification requirements, particularly when all authorized participants use consistent network rules.
Smart contracts can also automate selected workflows, including transaction approvals, digital asset transfers, and payment instructions.
Integrating blockchain applications with existing custom software solutions can connect these capabilities with ERP systems, financial applications, and customer platforms.
However, blockchain does not automatically make operations faster or cheaper. Businesses must consider network processing costs, transaction confirmation times, data storage, and integration requirements.
The most effective implementations target processes where shared verification provides a measurable advantage.
Challenges Businesses Should Consider Before Adopting Blockchain
Despite its potential, blockchain development involves technical, operational, and regulatory challenges.
Scalability: Different blockchain networks have different transaction processing capacities. Businesses must evaluate whether the network can support expected workloads.
Integration: Connecting blockchain applications with existing databases, payment gateways, and enterprise software may require additional development.
Security: Smart contract bugs, compromised cryptographic keys, and vulnerable applications can create significant risks.
Regulatory compliance: Laws concerning cryptocurrencies, digital assets, data privacy, and financial transactions vary across jurisdictions.
Implementation costs: Development, infrastructure, audits, maintenance, and employee training contribute to the overall investment.
Governance: Businesses must decide who controls network participation, software updates, transaction validation, and dispute resolution.
Addressing these factors early can help organizations avoid unnecessary complexity and develop more sustainable solutions.
How to Get Started With Blockchain Development?
Businesses considering blockchain should begin with a practical evaluation of their requirements.
1. Identify the business problem: Determine which existing process suffers from limited transparency, repetitive reconciliation, or inefficient coordination.
2. Evaluate blockchain suitability: Compare distributed ledger technology with conventional databases and existing software solutions.
3. Select the blockchain platform: Consider Ethereum, Hyperledger Fabric, or another suitable platform based on the application’s architecture and requirements.
4. Build a proof of concept: Develop a limited version to test the core functionality before committing to a larger implementation.
5. Integrate existing systems: Connect relevant ERP, CRM, payment, and business applications through APIs or integration services.
6. Test and deploy: Conduct functional, security, and performance testing before moving into production.
Businesses should measure results using relevant indicators such as transaction processing time, reconciliation effort, operational expenses, and error rates.
How Moon Technolabs Helps Businesses With Blockchain Development?
Moon Technolabs provides blockchain development services for businesses exploring decentralized applications, digital transactions, and blockchain-based enterprise solutions.
Its blockchain development services include custom blockchain software, digital wallets, payment platforms, tokenization, decentralized applications, and other blockchain-related solutions.
Businesses can work with Moon Technolabs to explore solutions across several areas:
- Custom Blockchain Development: Applications designed around specific operational and transaction requirements.
- Smart Contract Development: Automated blockchain-based workflows and programmable business agreements.
- Blockchain Wallet Applications: Digital asset storage, management, and transaction functionality.
- Tokenization Solutions: Systems supporting blockchain-based representation and management of eligible digital assets.
- Blockchain Integration: Connecting blockchain functionality with existing business software and enterprise applications.
The development approach should consider security, scalability, ease of use, and integration with existing technology infrastructure.
Rather than treating blockchain adoption as an isolated initiative, businesses can explore how the technology supports their broader digital transformation objectives.
Conclusion
Blockchain development is creating new opportunities for businesses by enabling shared transaction records, programmable agreements, digital asset management, and decentralized applications.
From financial services and supply chain management to healthcare and e-commerce, organizations can explore blockchain to address problems involving verification, transparency, and collaboration.
However, the technology delivers meaningful business value only when applied to suitable use cases. Organizations should evaluate costs, performance, security, regulations, and operational requirements before implementation.
For businesses planning blockchain adoption, the objective should be clear: build practical solutions that improve existing processes or create valuable new services.
Ready to explore blockchain opportunities for your business? Connect with Moon Technolabs to discuss your project requirements and identify a suitable development approach.